
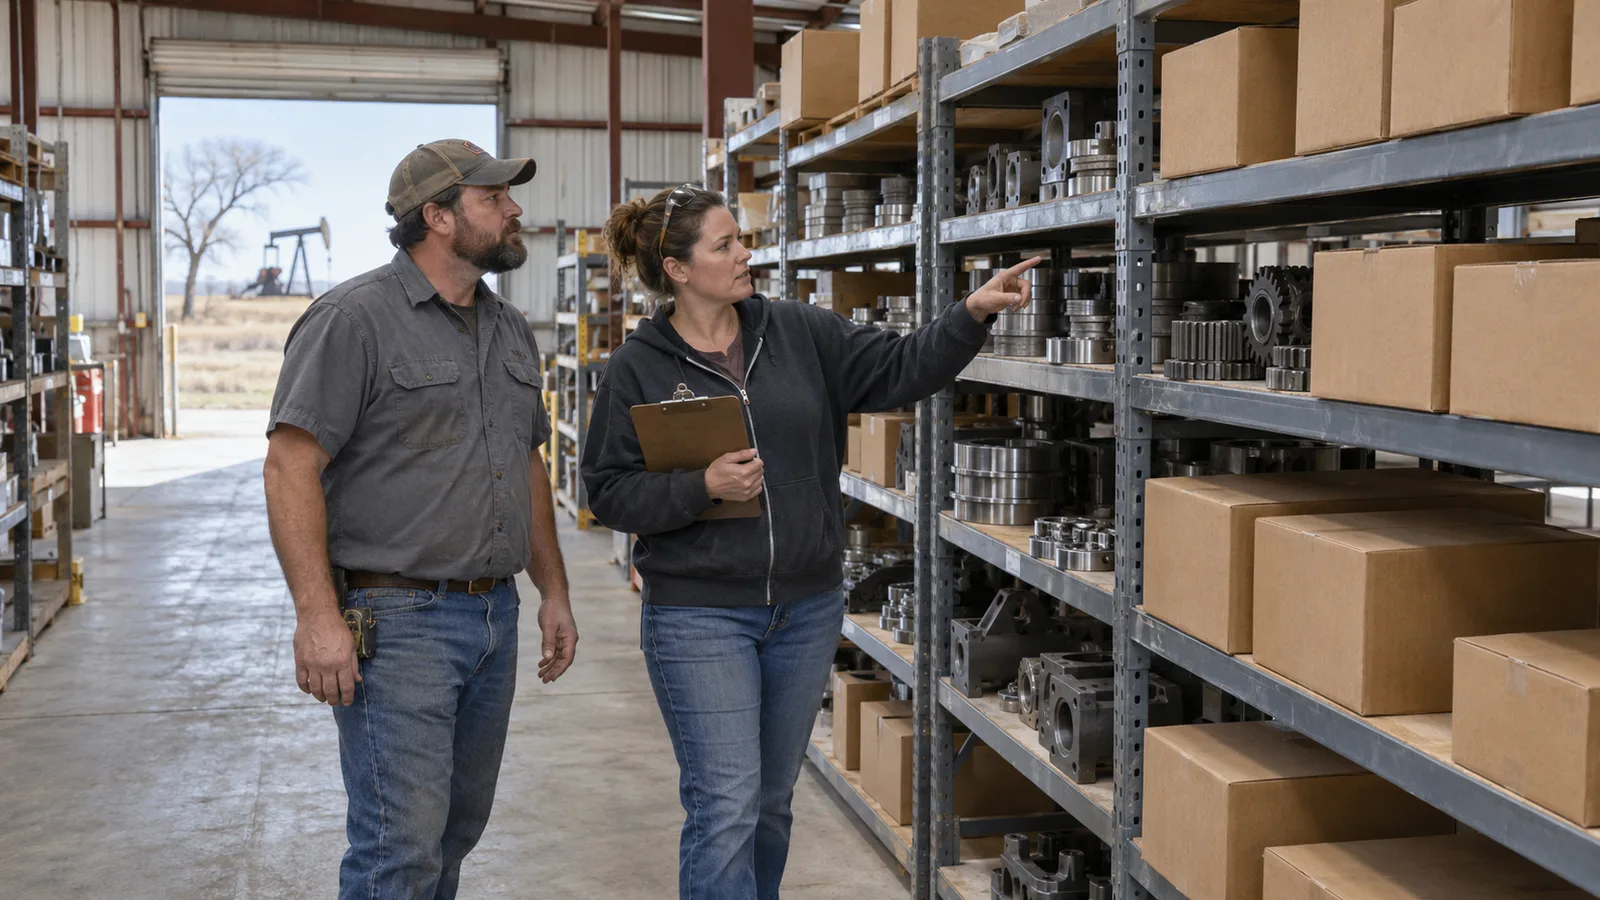
Reconcile stock to actual demand
Separate active stock from obsolete parts, damaged goods, and slow moving inventory. An accounting balance is a starting point. A buyer may ask for aging reports and a physical count before agreeing to pay for it.
Show reorder patterns, gross margins, and customer returns. Explain why stock is held and which products keep important accounts coming back. Avoid treating every box on a shelf as equally valuable.
Check the relationships that travel with the sale
Review supplier and distribution agreements for assignment, change of control, and territory restrictions. A buyer needs to know whether access to important product lines continues after closing.
List customer concentration and payment terms. Reliable revenue still consumes cash when customers pay well after suppliers must be paid. A business valuation should reflect that funding requirement.
Agree on the working capital formula
Decide how inventory, receivables, payables, and customer deposits enter the offer. Define a normal operating level from monthly figures rather than picking a closing date with unusually low inventory.
Document the counting method, disputed items, and any adjustment after closing. Your accountant should be involved before a letter of intent turns these points into a negotiation under deadline.
Keep the sales team focused
Prepare a private overview with product categories, earnings, and the reason for sale. Release customer names only at an appropriate stage. Decide how the buyer will meet key staff without starting rumors.
An organized transfer gives the buyer a way to evaluate the business beyond its stock value. It also helps you compare offers on the same economic terms.
Continue your sale preparation
Request a business sale introduction when you are ready to discuss your company.